UK Imposes Provisional Anti-Dumping Duties on Chinese Glass Bottles and Jars
Please note: the United Kingdom has formally published a provisional anti-dumping measure on certain glass containers originating in China. For covered bottles, jars and similar products, tax-included / DDP shipping is generally no longer workable. If goods move on a self-clearance basis, the UK importer must secure and, if confirmed, pay the anti-dumping duty.
On 8 September 2026, the Secretary of State accepted a recommendation from the Trade Remedies Authority (TRA) and published Trade Remedies Notice 2026/25. The provisional duty took effect on 9 September 2026. It can last for up to six months, or until a definitive measure is put in place, whichever comes first.
This is not a rumour or a carrier warning. It is an official UK trade-remedies notice applied by HMRC on import.
What Changed for Exporters
Many China-to-UK shipments of empty glass packaging previously moved on a “tax-included” or DDP basis, with the forwarder quoting an all-in price. That model is now breaking down for covered products:
- DDP / tax-included service: most agents will refuse new bookings, or will quote only after adding the anti-dumping amount and a guarantee fee. In practice, “包税不出” — the all-in channel is no longer available on normal terms.
- Self-clearance / DDU / DAP: the UK importer of record must declare the correct commodity code, pay ordinary import duty and VAT where due, and give HMRC a guarantee for the estimated anti-dumping duty.
The guarantee can be a bank guarantee, bond or cash deposit. The guaranteed amount only becomes payable if a definitive duty is later imposed. If no definitive duty is imposed, or if the final rate is lower, HMRC can release or refund the difference through the usual channels.
Goods Covered
The official goods description is:
Carboys, bottles, flasks, jars, pots, phials, preserving jars, and other containers, of glass, of a kind used for the conveyance or packing of goods, whether or not including a closure.
Not covered:
- glass containers with a nominal capacity of 2.5 litres or more
- ampoules
- tubular glass containers
- standalone glass stoppers, lids or other glass closures sold separately
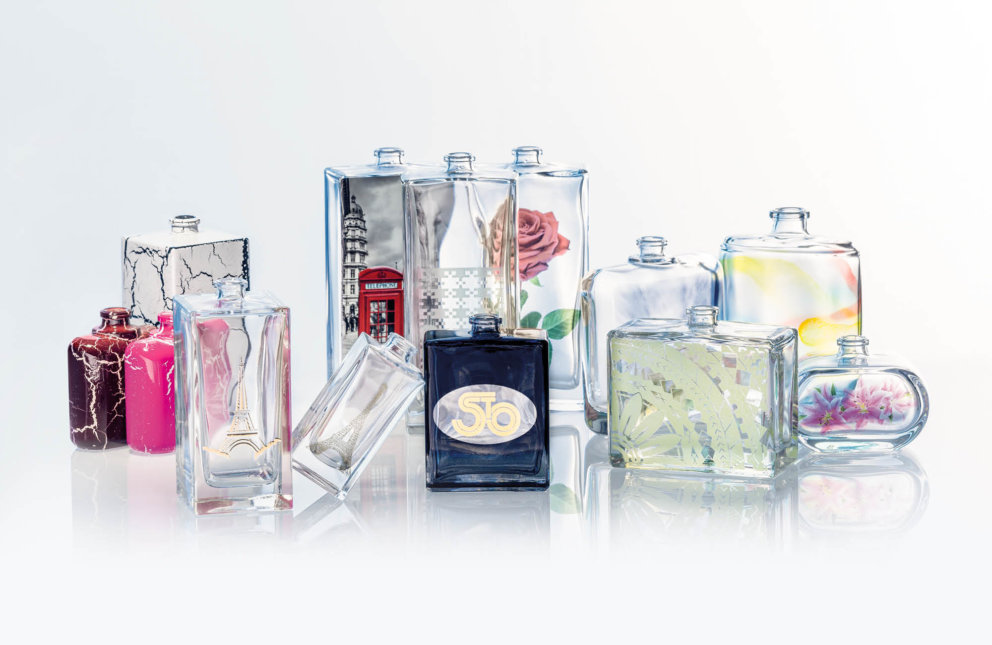
Typical commercial products in scope include food jars, preserve jars, cosmetic and perfume bottles, and other packing glass below 2.5 litres.
Commodity Codes
Imports declared under the following UK Global Tariff codes are in scope when the goods match the description and originate in China:
- 7010 9010 00
- 7010 9041 00
- 7010 9043 00
- 7010 9045 00
- 7010 9047 00
- 7010 9051 00
- 7010 9053 00
- 7010 9055 00
- 7010 9057 00
- 7010 9061 00
- 7010 9067 00
- 7010 9071 00
- 7010 9079 00
- 7010 9091 00
- 7010 9099 00
The code alone is not enough. If the physical product falls outside the goods description — for example a 2.5-litre-or-larger container, an ampoule, or a separately sold glass lid — the measure should not apply. Those out-of-scope goods use additional code 8A96 at 0%.
Provisional Duty Rates
The duty is an ad valorem percentage of customs value. Official rates in Notice 2026/25 are:
| Exporter / producer | Provisional anti-dumping duty | Additional code |
|---|---|---|
| Huaxing Group | 26.87% | 8A92 |
| SPG Group | 24.65% | 8A93 |
| Non-sampled co-operating exporters / producers | 25.88% | 8A94 |
| All other overseas exporters | 52.97% | 8A95 |
| Goods outside the goods description | 0.00% | 8A96 |
To claim a named-company rate, the import must be supported by a valid commercial invoice and the producer declaration set out in the notice. If that paperwork is missing, HMRC applies the residual rate of 52.97%.
Public summaries have referred to duties “up to 53%.” That figure is the residual rate of 52.97%, rounded. Co-operating producers face lower rates of about 25% to 27%.
What Buyers and Sellers Should Do Now
- Check every SKU against the official description and the 15 commodity codes above. Do not assume all “glass bottles” are in or out of scope.
- Stop quoting all-in DDP prices that ignore the anti-dumping amount.
- Tell UK customers that they, as importer of record, must arrange the HMRC guarantee and declare the correct additional code.
- Identify the Chinese producer. If it is not Huaxing Group, SPG Group, or another co-operating exporter, budget for 52.97%.
- Put the producer name, address and additional code on the commercial invoice, with the signed declaration required by the notice.
- Recalculate landed cost: customs value × provisional ADD, plus ordinary duty and VAT where applicable.
- Watch the TRA case file AD0087. This is still a provisional measure. A final duty, a change in rate, or no definitive duty remain possible.
Background
TRA opened anti-dumping case AD0087 on 5 March 2026. Imports from China were registered from 24 March 2026 under Trade Remedies Notice 2026/12. The TRA’s preliminary finding is that the goods have been dumped and have injured the UK industry. Sampled UK producers in the case employ about 2,099 people and generate about £244 million in gross value added.
A separate UK case, AS0088, looks at alleged subsidised glass containers from Turkey. That investigation is not the same as this China anti-dumping duty.
Companies should rely on the GOV.UK notice and HMRC declarations, not on informal shipping-group summaries. Classification, origin and the invoice declaration will decide whether 24.65%, 26.87%, 25.88%, 52.97% — or 0% — applies to a given shipment.